Table of contents
- 1. Start With Businesses People Always Need
- 2. Choose an Industry Before Searching
- 3. Define What Makes a Good Acquisition
- 4. Search Business Marketplaces Strategically
- 5. Find Owners Before They Advertise
- 6. Use Brokers Without Losing Control
- 7. Evaluate the Business Behind the Listing
- 8. Measure the Risks That Numbers Hide
- 9. Calculate What You Can Actually Afford
- 10. Negotiate Only After Due Diligence
- 11. Avoid the Most Expensive Mistakes
- 12. Make the Numbers Earn Your Confidence
- Frequently Asked Questions
1. Start With Businesses People Always Need
Look for companies that solve recurring problems, provide essential services, and earn revenue without depending on constant public attention.
Think commercial cleaning, pest control, plumbing, waste collection, accounting, equipment maintenance, and specialized distribution.
These businesses rarely attract the excitement associated with technology startups, fashionable consumer brands, or rapidly growing online companies.
Their appeal comes from something more practical: customers need their services whether the economy is booming or slowing down.
A boring business is not automatically a good investment.
A company can operate in an essential industry and still have weak margins, unreliable customers, expensive equipment, poor management, or excessive debt.
The objective is to find a business with dependable demand, understandable operations, defensible customer relationships, and enough financial evidence to justify its purchase price.
For an individual buyer, this search can be particularly attractive.
Instead of creating a company from nothing, you may be able to acquire an established operation with employees, customers, supplier relationships, equipment, and an existing record of revenue.
That can shorten the path to operating a business, although it does not eliminate the risks of ownership.
Begin by identifying services that businesses and households purchase repeatedly.
Then narrow the search to companies that have operated long enough to demonstrate a consistent record of performance.
Look for owners who want to retire, simplify their lives, or move on to another opportunity.
Finally, verify the numbers before becoming emotionally attached to a particular acquisition.
The best opportunity is rarely the company with the most impressive sales presentation.
It is the one whose customers keep paying, whose costs are understood, whose operations can survive a change of ownership, and whose cash flow can support both the purchase price and your future responsibilities.
2. Choose an Industry Before Searching
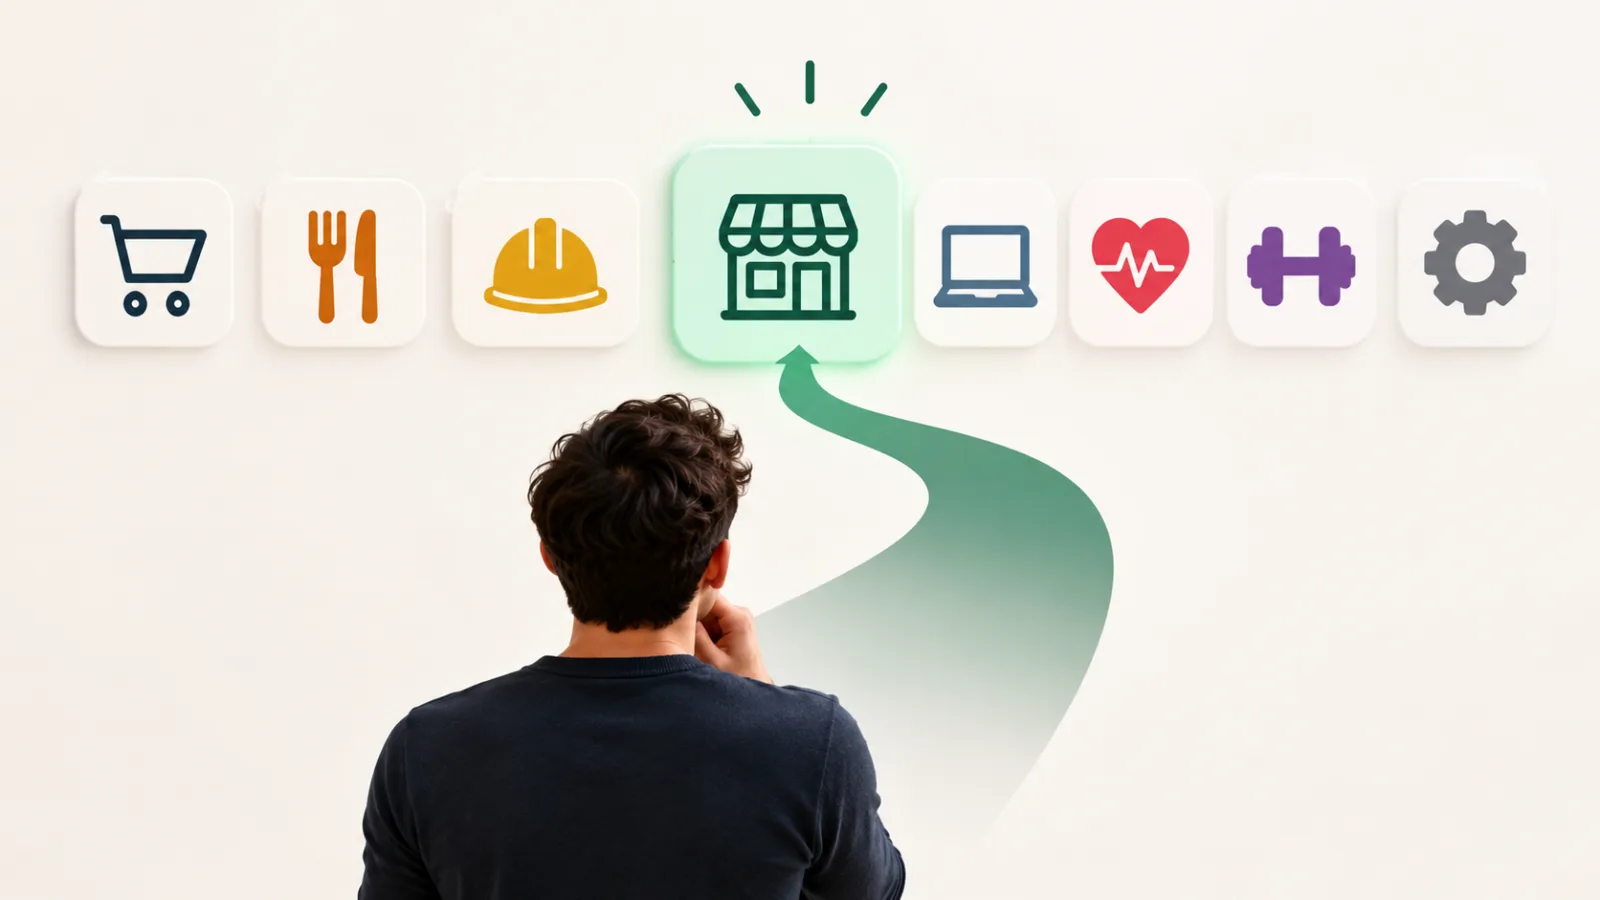
Searching every available business listing creates unnecessary work.
A more effective approach is to select a small group of industries, understand their economics, and concentrate your search on companies that fit your financial resources and operating abilities.
Several industries are worth investigating because their services are recurring, practical, or difficult for customers to avoid.
Commercial cleaning: Offices, medical facilities, schools, warehouses, retail locations, and industrial buildings need regular cleaning.
Contracts can produce predictable revenue, but profitability depends on labor costs, contract pricing, employee reliability, and the ability to retain clients.
Pest control: Residential and commercial customers need treatment, prevention, and monitoring.
Recurring service agreements can improve revenue visibility.
Buyers must examine licensing requirements, chemical handling obligations, technician availability, customer retention, and the cost of acquiring new customers.
Plumbing and HVAC maintenance: Buildings require repairs, inspections, and equipment servicing.
Emergency work can generate valuable revenue, while maintenance agreements may support repeat business.
However, skilled labor shortages, vehicle expenses, seasonality, and dependence on licensed technicians can materially affect performance.
Waste management and collection: Commercial customers may require scheduled collection, disposal, recycling, or specialized waste services.
Contracts and established routes can be attractive, but vehicles, fuel, disposal fees, permits, environmental obligations, and equipment replacement can make these businesses capital intensive.
Accounting and bookkeeping: Small companies need help maintaining records, managing payroll, preparing financial reports, and meeting tax obligations.
Recurring client relationships can be valuable, although seasonal demand, professional qualifications, data security, and dependence on the owner deserve careful examination.
Equipment repair and maintenance: Factories, restaurants, farms, workshops, and commercial facilities depend on machinery that must be maintained.
Specialized technical knowledge can make a service provider difficult to replace.
The challenge is determining whether that knowledge belongs to the business or resides almost entirely in one individual.
Specialized distribution: Some companies supply replacement parts, packaging materials, industrial consumables, safety equipment, or other products that customers purchase repeatedly.
These operations can benefit from long standing supplier relationships and established accounts.
Inventory quality, supplier concentration, customer credit, and working capital require particular attention.
Property maintenance: Businesses that maintain commercial buildings, grounds, parking facilities, or shared residential spaces may generate recurring contracts.
Their economics depend on labor productivity, contract renewal rates, equipment needs, and geographic concentration.
Laundry and linen services: Hotels, restaurants, healthcare facilities, and other organizations may need regular linen cleaning and replacement.
Established contracts can provide repeat demand, but machinery, utilities, water consumption, maintenance, and transportation can absorb substantial cash.
Inspection and compliance services: Certain industries require periodic inspections, testing, documentation, or equipment certification.
Where qualifications and regulation create meaningful barriers to entry, an established provider may have a defensible position.
Confirm the precise requirements in the relevant jurisdiction before evaluating a company.
Do not choose an industry simply because it appears recession resistant.
Determine whether customers pay reliably, whether the service can be delivered profitably, and whether you can supervise the operation competently.
A useful starting point is to select three industries.
Research typical customer relationships, labor requirements, licensing rules, major operating costs, and common reasons businesses fail.
This gives you enough focus to recognize attractive opportunities without restricting yourself to one narrow category.
3. Define What Makes a Good Acquisition
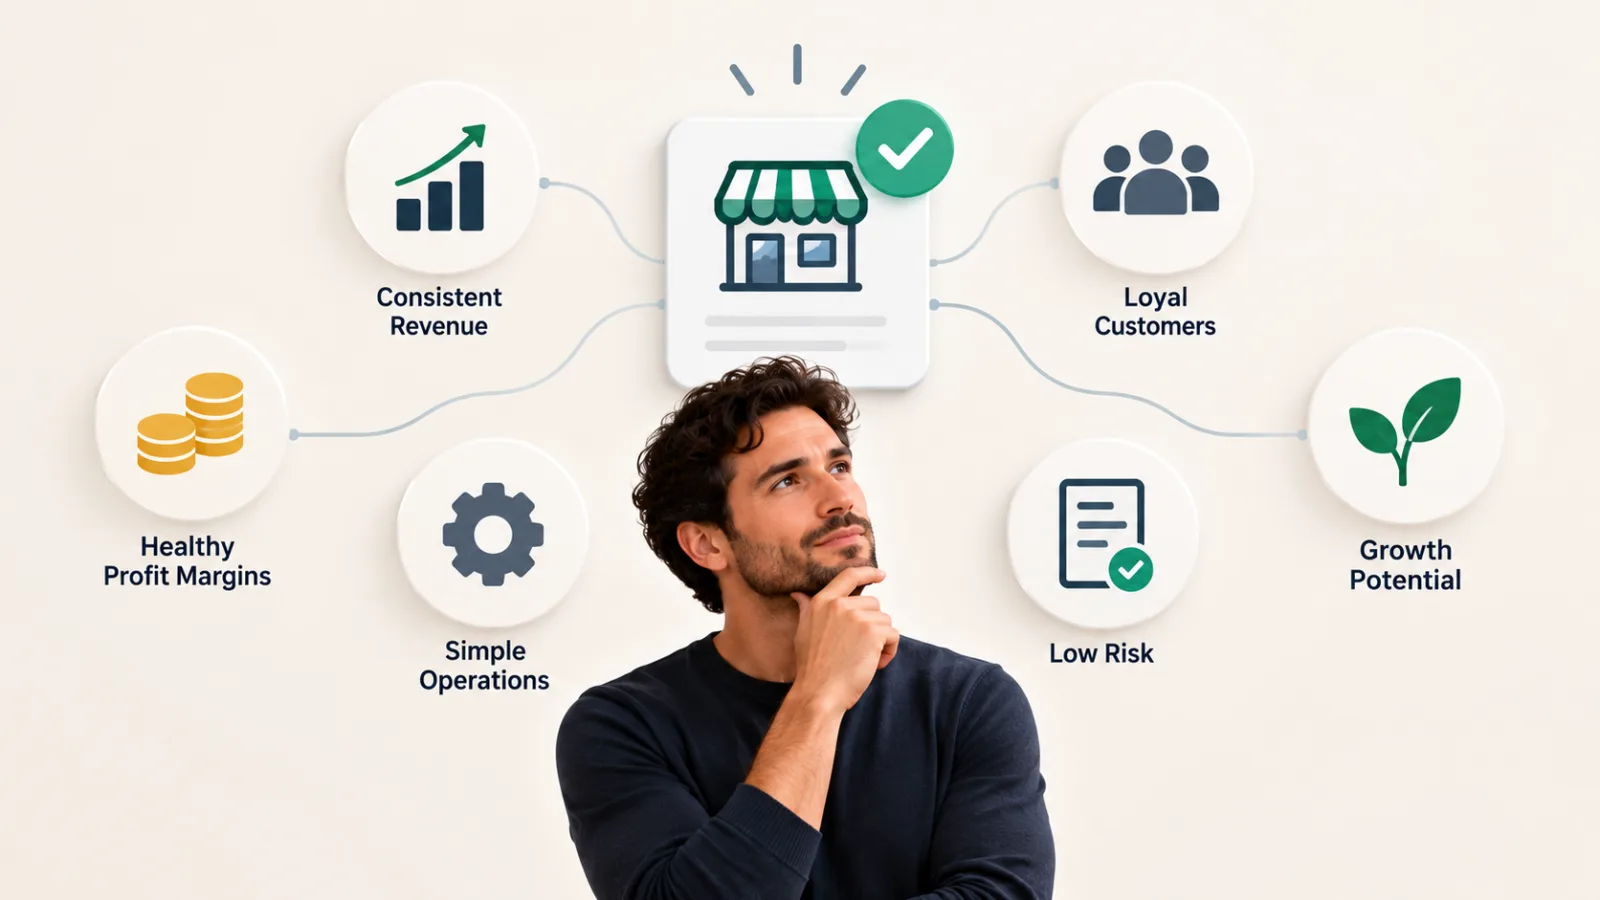
Before contacting sellers, write down the characteristics of a business you would genuinely consider buying.
Without clear criteria, buyers can spend months examining companies that are too expensive, too complex, or poorly suited to their circumstances.
Start with your available capital.
The purchase price is only one part of the financial commitment.
You may also need money for professional fees, financing costs, inventory adjustments, equipment repairs, employee retention, insurance, and working capital after completion.
A company that consumes all your available cash at closing may become difficult to operate even when its underlying business is healthy.
Establish a reserve that reflects the company's actual operating needs rather than assuming that the first month will proceed exactly as forecast.
Next, determine the size of business you can manage.
A small local service company with a handful of employees requires different skills from a regional distributor with multiple locations, a large inventory, and complex supplier relationships.
Revenue alone is a poor measure of suitability.
A business generating substantial sales may produce little cash after paying employees, suppliers, rent, taxes, maintenance, and debt service.
Another company with lower revenue may have simpler operations and stronger margins.
Set criteria around the following areas:
Financial performance: Require credible financial records and a reasonable explanation for changes in revenue, margins, and operating expenses.
Revenue quality: Prefer repeat customers, documented contracts, reliable payment patterns, and a manageable level of customer concentration.
Owner dependence: Determine whether employees can handle customer service, scheduling, sales, technical work, and daily decisions without constant intervention from the current owner.
Operating complexity: Understand staffing requirements, inventory, vehicles, equipment, premises, permits, and the number of moving parts involved in delivering the service.
Growth opportunities: Look for realistic improvements, such as better scheduling, more consistent pricing, additional sales to existing customers, or expansion into nearby service areas.
Seller motivation: Establish why the owner wants to sell and whether the proposed transition is practical.
Risk exposure: Identify pending disputes, customer complaints, regulatory obligations, outdated equipment, environmental concerns, and other liabilities.
Personal fit: Decide whether you can manage the industry, employees, customers, and operating schedule for several years.
Your criteria should also include deal breakers.
These might include missing financial statements, unexplained cash transactions, a customer responsible for most of the revenue, or an owner unwilling to provide information during due diligence.
The purpose is to reject unsuitable opportunities early.
A disciplined buyer does not need to investigate every company in detail.
You need enough information to identify which sellers deserve a serious conversation.
4. Search Business Marketplaces Strategically
Online marketplaces are an obvious starting point because they bring together businesses advertised for sale by owners, brokers, and intermediaries.
They also allow buyers to filter opportunities by location, industry, asking price, revenue, and reported earnings.
Several platforms can help you identify potential acquisitions.
BizBuySell is particularly relevant to buyers searching for established small businesses in the United States.
Listings span service companies, retail operations, manufacturing, distribution, and other sectors.
BizQuest provides another source of business listings, including local service businesses and established commercial operations.
BusinessesForSale.com covers multiple countries and industries.
It can be useful when the buyer is considering opportunities outside the United States or comparing different markets.
Acquire.com is more closely associated with digital businesses and technology companies.
It can be relevant when the definition of a boring business includes established software products or other recurring revenue businesses, but it is not a substitute for traditional local business listings.
Flippa is another option for digital assets, websites, ecommerce operations, and certain online businesses.
Buyers should distinguish between a business with transferable, dependable earnings and a website whose revenue depends on volatile advertising, search traffic, or a single acquisition channel.
Use the marketplaces that match your intended geography and business type.
A buyer looking for a local plumbing company should not spend most of their time reviewing software acquisitions simply because those listings are easier to browse.
Apply filters that reflect your criteria, but do not assume that marketplace information has been independently verified.
Advertised revenue and earnings are seller supplied unless the listing specifically establishes otherwise.
When reviewing a listing, ask yourself four questions.
First, does the business perform a service or sell a product that customers need repeatedly?
Second, does the listing provide enough financial information to justify contacting the seller?
Third, can you understand how the business makes money without relying on vague claims about its potential?
Fourth, does the opportunity appear compatible with your available capital, location, and operating abilities?
Save promising listings in a tracking document.
Record the asking price, reported revenue, stated earnings, location, industry, seller contact, date reviewed, and outstanding questions.
This creates a consistent process and makes it easier to compare opportunities objectively.
Do not treat the asking price as proof of value.
A seller may have selected a price based on personal expectations, an outdated valuation, or an optimistic interpretation of earnings.
Your job is to determine what the company is worth to you after accounting for its risks and financing requirements.
5. Find Owners Before They Advertise
Some attractive businesses never appear on public marketplaces.
Their owners may be considering retirement, struggling with succession planning, or willing to sell if approached by a credible buyer.
Others prefer a confidential sale because employees, customers, suppliers, and competitors do not need to know that a transaction is being considered.
Direct outreach can help you find these opportunities.
Start by identifying established businesses in your chosen industries and geographic area.
Local business directories, industry associations, trade events, professional advisers, and company websites can reveal potential targets.
Public business registries may help establish how long a company has operated, although the information available varies by jurisdiction.
Look for businesses that have a clear service offering, a history of operation, and an identifiable customer base.
A company that has served the same region for fifteen years may deserve investigation, but longevity alone does not establish profitability or sale readiness.
Once you identify a target, contact the owner professionally.
Explain that you are interested in acquiring an established business in the industry, provide a brief description of your background, and ask whether the owner would consider discussing a future sale.
Avoid making an aggressive offer before understanding the business.
An unsolicited message that immediately asks for financial statements or proposes a valuation can undermine trust.
A better initial conversation focuses on the owner's plans.
Are they considering retirement?
Do they have a succession arrangement?
Would they be interested in a confidential conversation about a potential sale, either now or in the future?
If the owner is not interested, respect that decision.
Ask whether you may reconnect later if appropriate.
Direct sourcing takes patience.
Many owners will not respond, some will decline, and others will express interest without being ready to transact.
Maintain a record of conversations and follow up only when it is reasonable and welcome.
Local accountants, commercial lawyers, business brokers, and other advisers may also know owners who are considering a sale.
Build relationships with professionals who work with established small businesses, explain your acquisition criteria, and demonstrate that you can evaluate opportunities responsibly.
Do not expect advisers to disclose confidential client information without permission.
Your goal is to become a credible potential buyer whom they can introduce when a suitable opportunity arises.
Direct outreach works best when it is specific.
Instead of contacting every small company in a city, focus on businesses that match your financial capacity, industry knowledge, and preferred operating model.
6. Use Brokers Without Losing Control
Business brokers can introduce you to opportunities, coordinate seller conversations, help manage confidentiality, and guide the transaction process.
An experienced broker may also understand the local market and know how different types of buyers evaluate a business.
However, brokers do not eliminate the need for independent analysis.
Understand whom the broker represents and how compensation works.
In many transactions, the seller engages the broker and pays the commission.
The broker may still be helpful to a buyer, but you should not assume the broker is acting as your independent financial adviser or negotiating exclusively in your interests.
Before investing substantial time in an opportunity, ask for basic information about the company, the reason for the sale, the asking price, the reported earnings, and the process for accessing further documentation.
You may need to sign a confidentiality agreement before receiving identifying details or sensitive records.
Read it carefully, particularly any provisions governing confidentiality, contact with employees or customers, and restrictions that could affect your future business activities.
Do not sign an agreement you do not understand simply because you want access to a listing.
Seek legal advice when the terms could materially restrict you.
Ask the broker how the asking price was determined.
Was it based on comparable transactions, an earnings multiple, asset value, or the seller's expectations?
What assumptions support the valuation?
Are the financial figures based on tax returns, internal statements, or a seller prepared summary?
A credible broker should be willing to explain the information available and identify what remains unverified.
Be cautious when a seller's earnings are presented as unquestionably reliable before financial records have been examined.
Also, understand the broker's role in managing competing offers.
A seller may receive several expressions of interest, and the process can move quickly.
Do not allow artificial urgency to replace proper diligence.
Your objective is to use the broker's access and transaction experience while retaining control over the decision.
Verify the financial information independently, engage your own advisers when necessary, and base your offer on evidence rather than enthusiasm.
7. Evaluate the Business Behind the Listing
A listing can make a business look attractive by emphasizing revenue growth, years of operation, a loyal customer base, or the possibility of expansion.
These details may be relevant, but they do not establish how much money the business actually generates for its owner.
Start with the financial statements.
Request income statements, balance sheets, cash flow information where available, and business tax returns for several years.
Three years is a useful starting point for many small business acquisitions, although the appropriate period depends on the industry, business history, and risks involved.
Ask for recent monthly results as well.
Annual figures can conceal seasonality, deteriorating performance, customer losses, or a sudden increase in expenses.
Compare reported revenue with the company's bank deposits, invoices, sales records, tax filings, and other supporting documentation.
The objective is to establish whether the business's reported performance can be substantiated.
Next, examine operating expenses.
Payroll, rent, insurance, materials, fuel, maintenance, software, subcontractors, and professional fees can significantly affect profitability.
Determine which expenses are necessary to continue operating the business after the sale.
Pay particular attention to the seller's claimed earnings.
Small business listings often present seller discretionary earnings, sometimes called SDE, or earnings before interest, taxes, depreciation, and amortization, known as EBITDA.
These measures are not interchangeable.
Seller discretionary earnings generally attempts to estimate the financial benefit available to one working owner by adding certain owner compensation and eligible discretionary expenses back to reported profit.
EBITDA measures earnings before interest, taxes, depreciation, and amortization, but does not automatically account for the cost of replacing an owner who performs essential work.
Both measures can be useful, provided you understand how they were calculated.
Ask for a detailed reconciliation between reported profit and the advertised earnings figure.
Review each adjustment individually.
An expense should not be excluded simply because the seller calls it unusual or discretionary.
For example, a seller may add back a personal vehicle expense, but the business might still require a vehicle after the transaction.
Similarly, removing the owner's salary from expenses may overstate the company's earning capacity if a replacement manager must be hired.
Suppose a business reports annual EBITDA of $180,000.
The seller asks you to value the company based on that figure.
However, the current owner personally manages scheduling, customer complaints, sales, and supplier relationships.
If replacing those responsibilities requires a manager costing $65,000 annually, the earnings available to a largely passive owner could be substantially lower than the advertised EBITDA suggests.
The precise adjustment depends on the work involved, local labor costs, and the responsibilities you intend to assume.
The important point is to value the business based on a realistic operating structure after the transaction.
Review working capital, inventory, accounts receivable, accounts payable, and outstanding obligations.
A profitable company can still experience cash shortages if customers pay slowly, suppliers demand faster payment, or inventory must be purchased well before revenue is collected.
Also examine capital expenditure requirements.
An older fleet of vehicles, worn production equipment, or an aging commercial property may require significant investment shortly after acquisition.
Accounting profit can look healthy while the actual cash required to maintain operations is substantial.
Finally, investigate customer concentration.
If one customer accounts for a large proportion of revenue, the business may be vulnerable to a single contract decision.
Review the contract terms, renewal history, payment record, and likelihood that the relationship will continue after the owner leaves.
Financial diligence should answer a central question: how much sustainable cash can the business generate after normal operating costs, necessary investment, and the cost of any work that must be replaced?
8. Measure the Risks That Numbers Hide
Financial statements reveal only part of a company's condition.
Some of the most important acquisition risks involve people, contracts, processes, and obligations that are difficult to identify from a profit and loss statement.
Begin with the owner.
Determine how much of the business depends on their personal relationships, expertise, reputation, or daily involvement.
Ask who quotes jobs, negotiates contracts, schedules employees, resolves complaints, maintains equipment, and wins new customers.
If the owner handles all these responsibilities, the business may be less independent than its financial results suggest.
A transition agreement can help, but it cannot guarantee that customers or employees will remain.
Establish which responsibilities the seller can transfer, how long assistance will be available, and whether key relationships can realistically survive the change in ownership.
Next, assess the workforce.
Review employee tenure, compensation, overtime, turnover, vacancies, and the availability of skilled replacements.
Determine whether the business relies on a small number of experienced employees whose departure would disrupt operations.
Confirm which employment obligations transfer to the buyer and whether the transaction structure changes those obligations.
The answer depends on the jurisdiction and whether the acquisition is structured as an asset purchase, a share purchase, or another arrangement.
Customer relationships require similar scrutiny.
Review contracts, renewal provisions, termination rights, pricing arrangements, service commitments, and any restrictions on transferring agreements.
Informal relationships may be valuable, but their durability should not be assumed.
Investigate supplier dependence as well.
A company that purchases most of its inventory from one supplier may face pricing pressure or disruption if that relationship changes.
Determine whether alternatives exist and whether supplier agreements continue after the sale.
Inspect the operational infrastructure.
Review equipment condition, maintenance records, vehicle history, software systems, cybersecurity practices, data handling, premises, and insurance coverage.
Identify overdue maintenance and upgrades that could become your responsibility.
Regulatory obligations deserve particular attention in industries involving chemicals, food handling, transportation, waste disposal, healthcare, construction, or professional services.
Verify permits, certifications, inspections, and any pending compliance matters with qualified advisers.
Also search for legal disputes, unpaid taxes, liens, outstanding loans, customer claims, employee disputes, and environmental liabilities where relevant.
A transaction agreement may allocate certain risks between buyer and seller, but contractual language does not automatically eliminate obligations imposed by law or liabilities associated with the acquired entity.
Do not assume that an asset purchase removes every historical risk, or that buying company shares simply transfers a clean operating business.
The consequences depend on the transaction structure, applicable law, and the specific liabilities involved.
The right professional team should help identify these issues before you commit to closing.
Your accountant can investigate financial records, your lawyer can examine contracts and liabilities, and relevant technical specialists can assess equipment or industry specific risks.
A boring business becomes attractive when its operations are understandable and its risks are manageable, not when those risks are hidden by a simple business model.
9. Calculate What You Can Actually Afford
A purchase price should be evaluated in relation to sustainable earnings, financing costs, working capital, and the return you require for taking ownership risk.
Start by determining the company's maintainable earnings.
This means estimating the profit the business can reasonably generate under normal operating conditions, after accounting for necessary expenses and a realistic management structure.
Do not automatically use the best year as the basis for valuation.
Examine several years of performance, investigate unusual changes, and determine whether recent growth is likely to continue.
Then consider comparable transactions.
Businesses in the same industry can sell at different valuations depending on their size, location, recurring revenue, customer concentration, margins, growth, management depth, and capital requirements.
Published asking prices are not the same as completed sale prices.
Where reliable transaction data is available, examine actual sales involving genuinely comparable businesses.
Treat broad industry multiples as reference points rather than universal rules.
Suppose a company generates maintainable annual EBITDA of $200,000 and a hypothetical valuation analysis supports a multiple of four times EBITDA.
That would imply an enterprise value of $800,000 before considering transaction specific adjustments.
This is an illustration, not a recommended market multiple.
Whether four times EBITDA is reasonable depends on the company's characteristics and the relevant market.
Enterprise value also differs from the amount of money required to acquire the business.
Existing debt, cash, working capital adjustments, transaction expenses, and the agreed treatment of assets and liabilities can change the final purchase consideration.
Consider how the acquisition will be financed.
Potential funding sources include personal capital, bank loans, seller financing, investors, and specialist acquisition financing where available.
Eligibility, terms, guarantees, and permitted structures vary by country and lender.
A seller may agree to receive part of the purchase price over time.
This can reduce the buyer's immediate cash requirement, but it introduces contractual obligations and potential disputes if the business underperforms.
The terms should be negotiated and documented with appropriate legal and financial advice.
Build a cash flow forecast that includes debt payments, taxes, capital expenditure, working capital needs, and compensation for the work you perform.
If you intend to leave an existing job, account for your personal living expenses as well.
Stress test the forecast.
What happens if revenue falls by 10 percent?
What if a major customer leaves?
What if two experienced employees resign or equipment needs replacing earlier than expected?
A business that remains financially viable under reasonable adverse conditions is generally more attractive than one that requires every assumption to be correct.
Finally, compare the expected return with the risks, the time commitment, and alternative uses of your money.
A business that produces a respectable accounting profit may still be an unattractive acquisition if it requires extensive personal involvement and leaves little cash after debt service.
10. Negotiate Only After Due Diligence
Once the business appears suitable and the financial information supports further investigation, begin structuring a potential transaction.
A letter of intent can summarize the proposed purchase price, transaction structure, expected financing, key conditions, and timetable.
Depending on its wording and jurisdiction, some provisions may be binding even when the overall proposal is described as nonbinding.
Have your lawyer review it before signing.
Use the due diligence period to verify the information that matters to your decision.
Review financial statements, tax records, customer agreements, employee obligations, equipment, intellectual property, insurance, permits, outstanding liabilities, and other material records.
If the business operates from leased premises, establish whether the lease can be assigned or whether the landlord's consent is required.
A company with valuable local customers may lose much of its appeal if it cannot remain at its existing location on acceptable terms.
If customer contracts are essential to revenue, determine whether they require consent before a change of control or assignment.
Confirm that any licenses and permits needed to operate will remain valid or can be obtained before completion.
The purchase agreement should address exactly what is being acquired.
Identify the included equipment, inventory, intellectual property, contracts, customer records, and other assets.
Specify the treatment of debt, cash, working capital, warranties, representations, indemnities, and any other material obligations.
An asset purchase and a share purchase can produce different tax, legal, financing, and operational consequences.
Do not select one structure simply because it appears simpler.
Obtain advice based on the business, jurisdiction, and transaction.
Negotiate the seller's transition responsibilities.
If the current owner is essential to maintaining customer relationships, agree on a realistic period of assistance and define what that assistance includes.
Where appropriate, discuss a retention arrangement, deferred consideration, or an earnout tied to future performance.
These mechanisms can help bridge a valuation disagreement, but they require careful drafting.
The parties must understand how performance will be measured, what happens if circumstances change, and how disputes will be resolved.
Do not waive important diligence simply to secure a deal.
If the seller refuses reasonable access to financial records, will not explain major discrepancies, or pressures you to close before key questions are answered, reconsider the transaction.
The purpose of due diligence is to establish what you are buying, what it is worth, and which risks you are accepting.
If the evidence changes, your offer should change too.
11. Avoid the Most Expensive Mistakes
The first common mistake is confusing a boring industry with a safe investment.
Essential services can still suffer from weak management, excessive competition, rising labor costs, poor pricing, and customer losses.
Industry demand is only the starting point.
The second is trusting advertised earnings without checking the underlying records.
Seller supplied financial information can contain errors, optimistic adjustments, or expenses that cannot realistically disappear after the acquisition.
Reconcile reported earnings to supporting documents and have an independent accountant examine material discrepancies.
The third is paying for growth that has not been demonstrated.
A seller may claim that the business could expand into new cities, add services, or win larger contracts.
Those opportunities may exist, but the buyer will have to fund and execute them.
Do not pay the seller as though uncertain future growth has already occurred.
The fourth is underestimating working capital.
Payroll, supplier invoices, fuel, rent, insurance, and inventory must be funded even when customers pay late.
Reserve sufficient cash for normal operations and unexpected expenses.
The fifth is buying yourself a demanding job without recognizing it.
If the company depends on the owner to handle every important function, you may be purchasing employment rather than a business that can operate with a manageable level of supervision.
That is not necessarily a bad decision, but the valuation should reflect the work involved.
The sixth is ignoring customer concentration.
A business may appear stable because one large client has provided substantial revenue for years.
If that client can cancel its contract immediately, the risk could be much greater than the financial statements suggest.
The seventh is assuming employees and customers will remain automatically.
Changes in ownership can create uncertainty.
Communicate appropriately, preserve service quality, and develop a transition plan that respects confidentiality and applicable employment obligations.
The eighth is relying on a seller's explanation of every problem.
Sellers can provide valuable context, but their statements should be verified where the issue materially affects value or risk.
The ninth is overlooking capital expenditure.
A company can show strong accounting earnings while operating aging equipment that will soon require expensive replacement.
Examine maintenance history and obtain independent inspections where appropriate.
The tenth is becoming emotionally committed too early.
Buyers sometimes justify warning signs because they have already invested weeks in a transaction.
Time spent evaluating a business is not a reason to purchase it.
Set clear conditions for proceeding.
If financial records cannot be reconciled, essential permits cannot be secured, a critical customer contract will not transfer, or the economics fail under reasonable assumptions, be prepared to walk away.
There will be other opportunities.
Preserving your capital and judgment is more valuable than completing a transaction simply because you want to own a business.
12. Make the Numbers Earn Your Confidence
Finding a boring business for sale is a search for durable economics, not an exercise in collecting attractive listings.
The most promising companies combine repeat demand, reliable customers, understandable costs, transferable operations, and financial records that stand up to scrutiny.
Choose a few industries, establish your acquisition criteria, and build a repeatable process for finding sellers.
Use marketplaces and brokers to identify opportunities, but also develop relationships with owners who may consider a confidential sale.
Evaluate every company against the same financial and operational standards.
Before making a commitment, establish how much cash the business can generate after normal expenses, management requirements, maintenance, taxes, and financing.
Investigate the people and contracts behind the revenue.
Understand what happens if a major customer leaves, equipment fails, or the current owner steps away.
You do not need to find the most exciting company in the market.
You need to find one whose economics make sense at a price you can afford, whose risks you understand, and whose operations you can realistically sustain.
A successful acquisition begins when the evidence supports the decision.
If the evidence does not support it, keep searching.